Compare Mortgage Rates Without a Credit Check
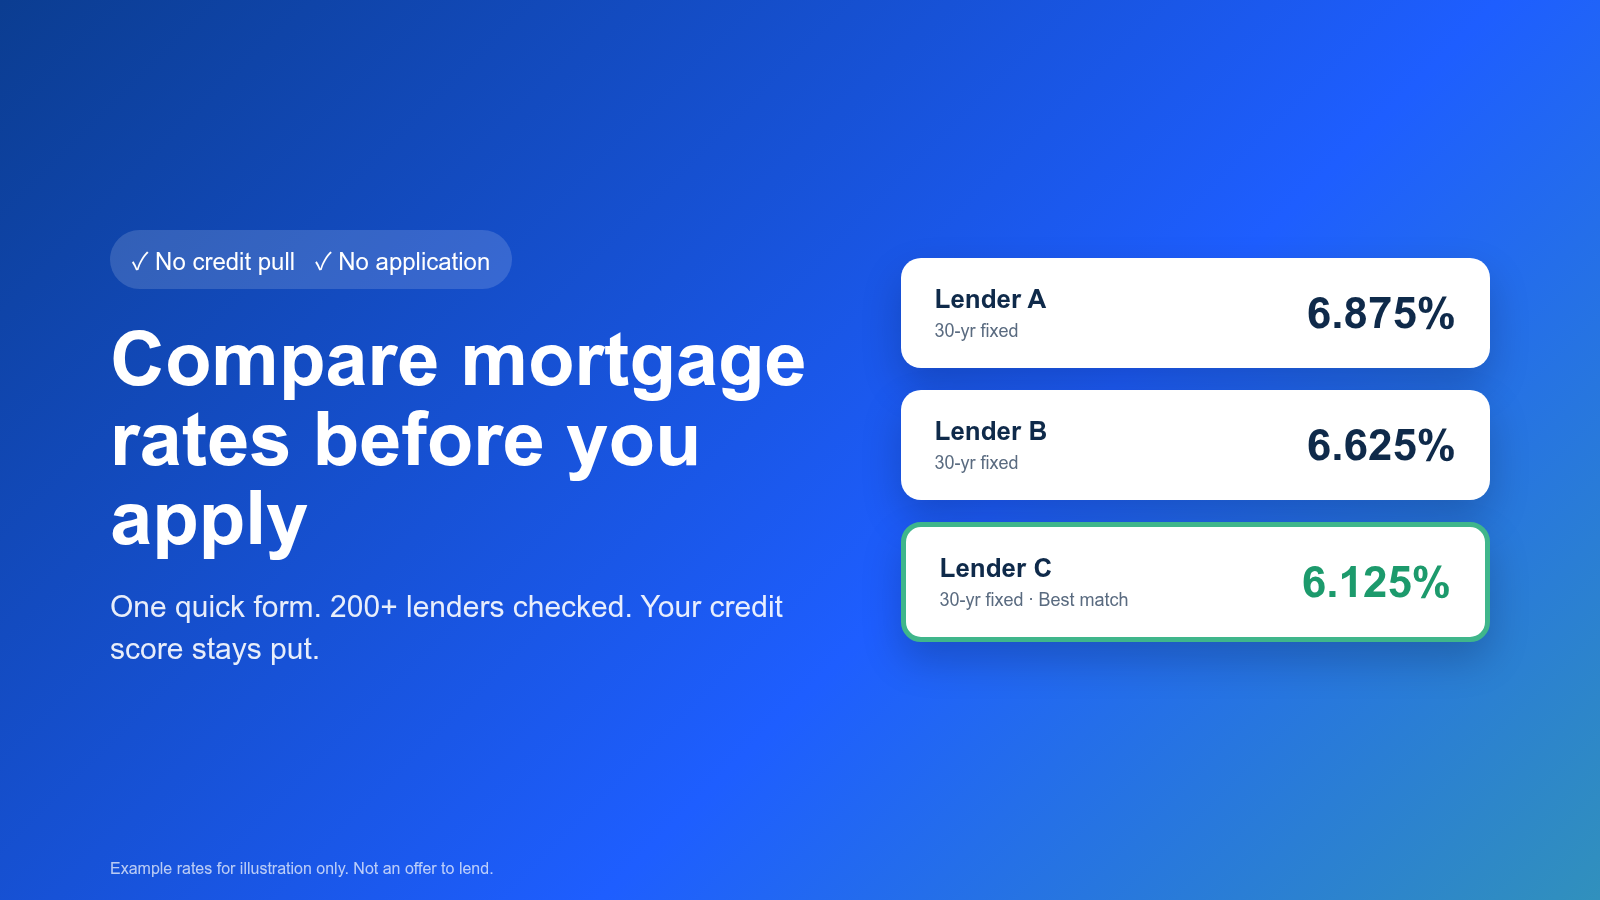
Here’s something most lenders would rather you didn’t know. Two people with the same credit score, the same income and the same house can get quoted rates that are half a point or more apart. The only difference is which lender they called first.
Most people call one lender, maybe two, and take what they’re given. That’s not because they’re careless. Every lender wants your Social Security number and a credit pull before they’ll show you anything real. After the third hard inquiry, most people give up and sign.
RateWing flips that around. You see the rates first. Then you decide who gets to pull your credit.
Why the first rate you get usually isn’t the best one
A mortgage officer at a bank can only show you their own bank’s rate. They’re not going to mention that the credit union across town is a quarter point lower this week, or that a wholesale lender would price your file better because you’re self-employed.
That gap costs real money. Freddie Mac looked at this. Borrowers who got just one extra quote saved about $1,500 over the life of the loan, and borrowers who got five quotes saved around $3,000. On bigger loans or tougher files, the gap is often wider.
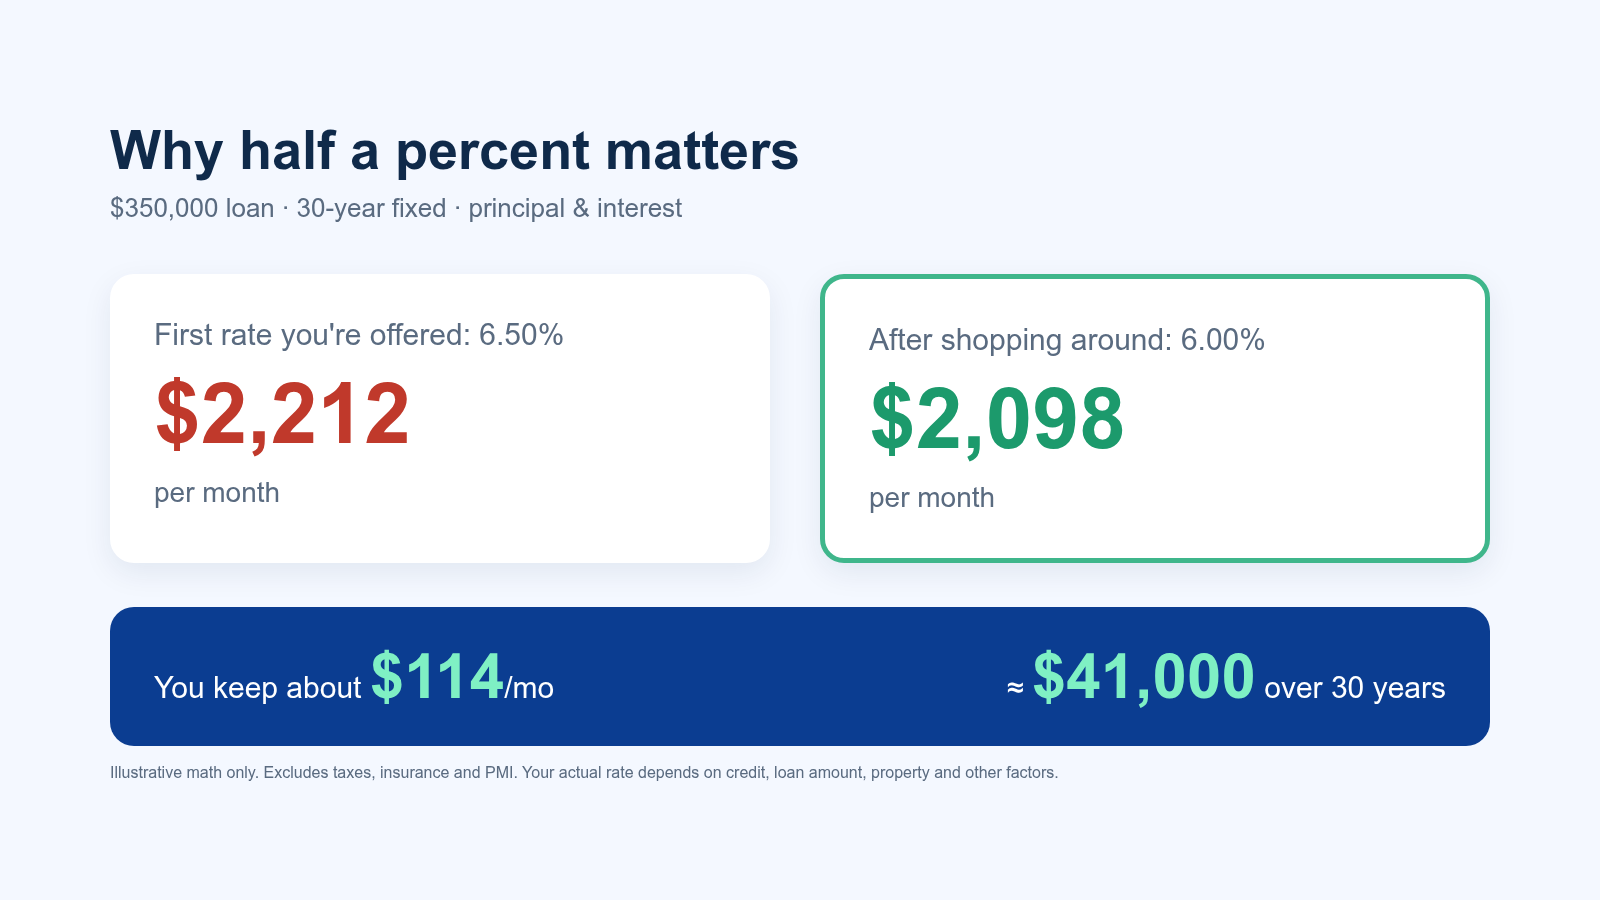
Run the numbers on a $350,000 loan. At 6.50% your principal and interest is about $2,212 a month. At 6.00% it’s about $2,098. That’s $114 a month back in your pocket, and close to $41,000 over 30 years, just for spending a few extra minutes shopping.
How to compare mortgage rates without a credit check
We built RateWing because getting a few honest quotes shouldn’t require handing your Social Security number to five strangers.
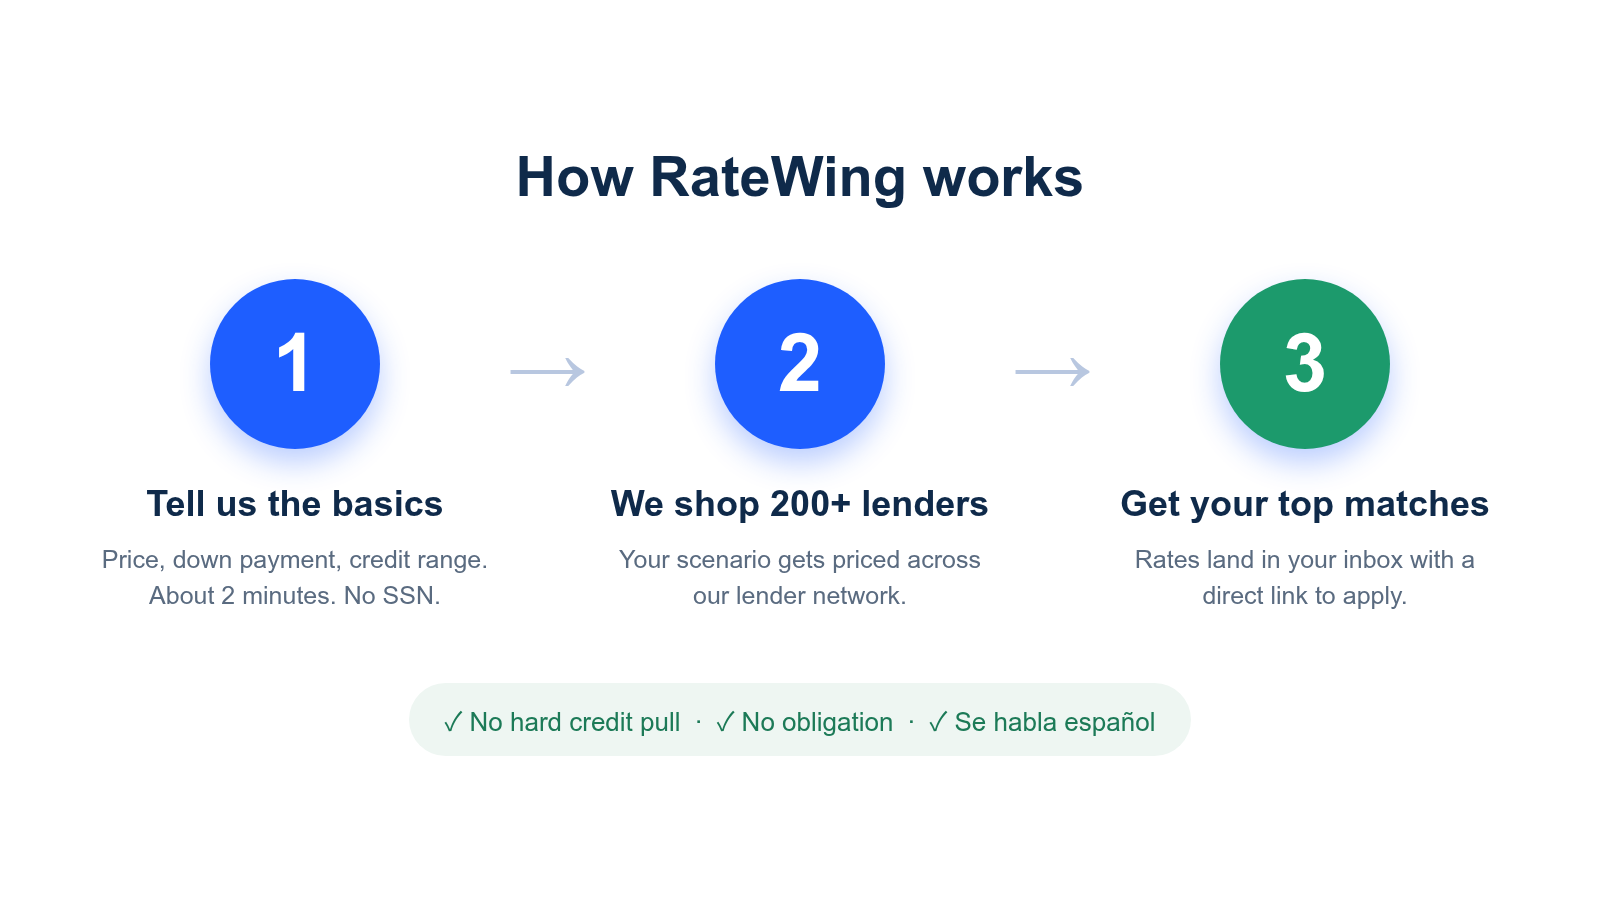
1. Tell us the basics. Home price, down payment, rough credit score, what kind of property it is, and whether you’re buying or refinancing. You don’t need an SSN or a pay stub. Most people finish in under two minutes.
2. We shop your scenario. We run your details across our network of 200+ lenders. That includes the big names, smaller wholesale lenders, and lenders who specialize in files that don’t fit the standard box.
3. You get your top matches by email. You’ll see the lenders that fit your profile best, with rates and terms side by side and a direct link to apply if you like one. Most people hear back within a few hours.
If something in the quote doesn’t make sense, a real person will walk you through it. We’ve been doing this for over 20 years, and yes, we can do it in Spanish too.
Does shopping for a mortgage hurt your credit?
This is the question we get most, so here’s the honest answer.
Getting a quote from RateWing doesn’t touch your credit at all. We don’t pull it. We price your scenario from the credit range you give us, which is why it helps to be as accurate as you can.
When you’re ready to apply with a lender, they will do a hard pull. That’s normal and you can’t avoid it. The credit scoring models are built for rate shopping, though. Newer FICO versions count multiple mortgage inquiries within a 45-day window as a single inquiry. Older versions use 14 days. So once you’re seriously shopping, it pays to do your applications close together.
The smarter move is to narrow your list before anyone pulls your credit. That’s the point of RateWing.
What actually changes your mortgage rate
When we compare quotes for you, these are the things that move the number most:
- Credit score. Pricing usually shifts every 20 points or so. Going from 679 to 680 can matter more than you’d think.
- Down payment. Putting 20% down usually gets you better pricing and no private mortgage insurance (PMI). But FHA and other low-down-payment loans can still come in competitive.
- Loan type. Conventional, FHA, VA, jumbo, bank statement and ITIN loans are all priced differently.
- Property type. A single-family home you’ll live in prices better than a condo or an investment rental.
- Points and lender credits. One lender’s “lower rate” may just mean you’re paying more upfront. We show you both sides so you can compare them fairly.
Who RateWing is built for
Honestly? Anyone who doesn’t want to overpay. But we’re especially useful if:
- You’re buying your first home and want to know what’s realistic before you talk to a loan officer
- You’re self-employed and the big banks keep asking for tax returns that don’t show what you really earn
- You’re using an ITIN instead of a Social Security number. We have lenders who do this every day.
- You already have a quote from your bank or a builder’s lender and want to know if it’s actually a good deal
- You’re thinking about refinancing and want a quick check without starting a full application
Already have a quote from another lender?
Good. Bring it.
Some of our favorite clients come in with a Loan Estimate in hand from someone else. We’ll run the same scenario and tell you straight whether your offer is solid or whether there’s money left on the table. If your current lender is already the best, we’ll say so. Either way, you’ll know.
Common questions
Is this really free?
Yes. You don’t pay anything to get a quote or compare lenders, and you’re never obligated to apply.
Will I get a flood of calls?
No. We don’t sell your info to a lead marketplace. You get your results by email, and someone from our team follows up personally. We don’t hand you off to a dozen call centers.
How accurate are the rates?
They’re based on what you tell us, so the closer your credit estimate and numbers are, the closer the quote will be. Final rates depend on your full application, appraisal and underwriting, and they can change with the market.
Can I compare refinance rates too?
Yes. Pick “refinance” on the form and we’ll shop rate-and-term or cash-out options for you.
Do you work with buyers outside Texas?
We’re licensed in multiple states. Fill out the form and we’ll confirm whether we can help where you’re buying.
See your rates before you commit to anything
It takes two minutes, there’s no credit pull, and you’re under no obligation. Worst case, you find out your current offer is a good one.
Rates shown are based on information you provide and can change without notice. Your actual rate depends on credit history, loan amount, property type and other factors. This isn’t a commitment to lend. NMLS #1328438. Equal Housing Opportunity.